April 2026 · U.S. economy · Monthly recap
Price pressure continued beyond March
Inflation remained elevated, with energy making another substantial contribution.
April’s monthly inflation increase was smaller than March’s, but it was still substantial. The annual rate rose again. That combination is worth understanding: a slower monthly increase can coexist with a worsening twelve-month comparison.
What happened to prices?
Consumer prices rose 0.6% over the month, after seasonal adjustment. The price basket was 3.8% higher than a year earlier, before seasonal adjustment. BLS reported that energy rose 3.8% in April and accounted for more than 40% of the overall monthly increase. BLS price report.
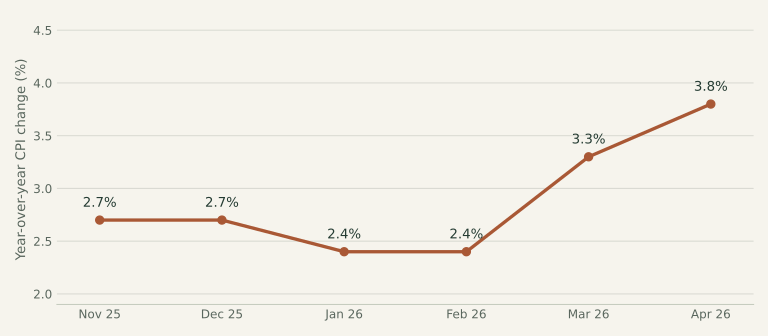
View the chart data and sources
| Month | Annual CPI | Source |
|---|---|---|
| November 2025 | 2.7% | BLS release ↗ |
| December 2025 | 2.7% | BLS release ↗ |
| January 2026 | 2.4% | BLS release ↗ |
| February 2026 | 2.4% | BLS release ↗ |
| March 2026 | 3.3% | BLS release ↗ |
| April 2026 | 3.8% | BLS release ↗ |
What happened to jobs?
The linked release reported 115,000 more nonfarm payroll jobs. The unemployment rate was 4.3%. BLS employment report.
What happened to interest rates?
The Federal Reserve held its target range at 3.50–3.75%. This is a benchmark for overnight bank lending, not the interest rate every consumer pays. Federal Reserve statement.
What this means in everyday life
Energy prices continued to put pressure on the headline index. For households, a second month of increases can matter more than the fact that the percentage is below the previous month’s peak. The employment gain offered some support to the income side of the picture, but it did not erase the extra pressure on expenses.
One thing to keep in mind
The key distinction is between the pace of new increases and the level of prices already reached. Less acceleration is helpful; it does not mean earlier cost increases have been reversed.
From the headlines to the classroom
AP Macro & Micro connections
Energy costs, supply shocks & production costs
AP Macro · Unit 3 · National Income and Price Determination
An increase in a widely used input cost can shift short-run aggregate supply left, raising the price level and reducing real output in the basic AD–AS model, all else equal. A cost decline can work in the opposite direction. The model helps explain a possible mechanism; CPI alone does not establish the cause of a real-world shock.
AP Micro · Unit 2 · Supply and Demand; 3 · Production, Cost, and the Perfect Competition Model
Fuel can be a variable input for a firm. A higher input price can raise marginal cost and reduce supply. However, the market price of fuel can also rise because demand increased, so a price change alone is not enough to identify a supply shift.
Try it yourself
Assume oil becomes more expensive because supply is disrupted. On an AD–AS graph with AD unchanged, what happens to SRAS, the price level, and real output?
Reveal the explanation
SRAS shifts left. The equilibrium price level rises and real output falls in the short run. Label the vertical axis Price level and the horizontal axis Real GDP, and show both equilibria. The supply disruption is an assumption in this question.
Sources & reporting notes
BLS Consumer Price Index — April 2026 ↗BLS Employment Situation — April 2026 ↗Federal Reserve decision — April 2026 ↗This is a retrospective, researched on October 6, 2026. Figures describe the month named above, unless a different period is stated. CPI and employment values are as reported in the linked archived releases; later revisions may differ. This recap focuses on prices, jobs, interest-rate decisions, and selected policy changes. It is educational, not personalized financial advice.
Check your understanding
The three-question quiz
One question about the recap, one about AP Macro, and one about AP Micro. These are original learning questions.